When you rent a car,
they always ask at the end.
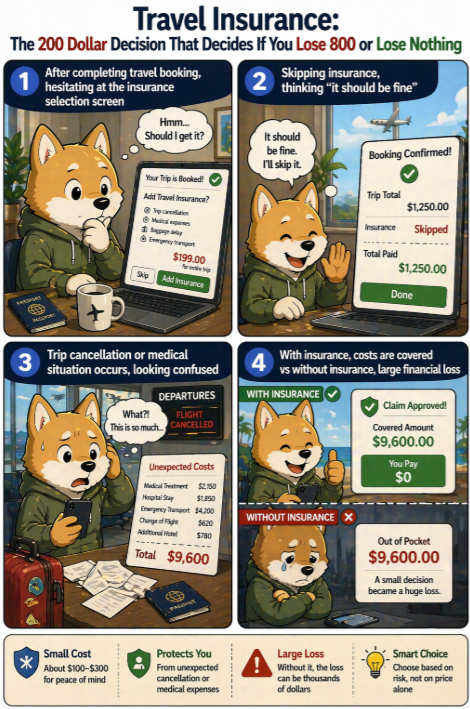
Would you like to add insurance?
It’s 30 dollars per day.
Most people just add it.
But with this one choice,
you either buy coverage you already have again,
or drive with no protection at all.
This is not about whether to buy insurance.
It is about paying twice because you didn’t know what you already have.
Q. Isn’t it safer to just add rental car insurance?
A.
At first, that’s what people think. In a foreign country, accidents feel complicated, so adding it seems easier. I thought the same.
When I rented a car in Italy, I was offered insurance for 25 dollars per day. I added it without much thought. It was 5 days, so 125 dollars.
Later, while checking my card statement, I realized something.
The card I used already included rental car damage coverage.
I had bought the same coverage twice.
What I realized was simple.
This is not buying safety. It is a structure where you pay more because you didn’t check.
So this is what I do.
Before adding insurance, I first check what coverage I already have.
Q. Is rental car insurance included in cards actually usable?
A.
If the conditions are met, it is fully usable. Especially abroad.
I once had a scratch on a car in Europe, and I saw it handled through card insurance.
It was resolved without the rental company’s insurance.
But there are conditions.
You have to pay the full rental with that card,
and the country must be within the coverage area.
If you don’t know this, you can’t decide on the spot.
So this is what I do.
Before booking a rental car, I check the card terms in advance.
Q. Then does that mean you should never buy rental car insurance?
A.
No. It depends on the situation.
If there is no card coverage, or if the card only provides secondary coverage, like in some domestic rentals, it’s different.
When I rented a car in the U.S., my card was secondary coverage. That means my own insurance applies first, and the card covers the rest.
In that case, some burden still remains.
So this is what I do.
I first check whether the card is primary or secondary coverage, then decide.
Q. What is the most common thing people miss?
A.
They misunderstand the coverage scope.
Rental car insurance often only covers vehicle damage.
Injury or damage to other vehicles is separate.
When I didn’t know this, I assumed it was “full coverage,” but in reality, it only covered part.
So this is what I do.
I look at vehicle damage and liability coverage separately.
Q. How big does the cost difference get?
A.
You feel it immediately.
30 dollars per day
is 150 dollars for 5 days,
and 210 dollars for 7 days.
I once rented a car for 7 days with insurance included, and later saw that almost half of the rental cost was insurance.
What I realized was this.
This may not be a safety cost. It can be a duplicated cost.
So this is what I do.
The longer the rental period, the more carefully I look at insurance.
Q. Then how should you make the final decision?
A.
It’s simple.
If you already have coverage, don’t add it.
If you don’t have coverage, add it.
This is not a choice issue.
It is a confirmation issue.
So this is what I do.
Before I’m asked at the counter, I already know the answer.
Published date
2026-04-27